What Is Bookkeeping?
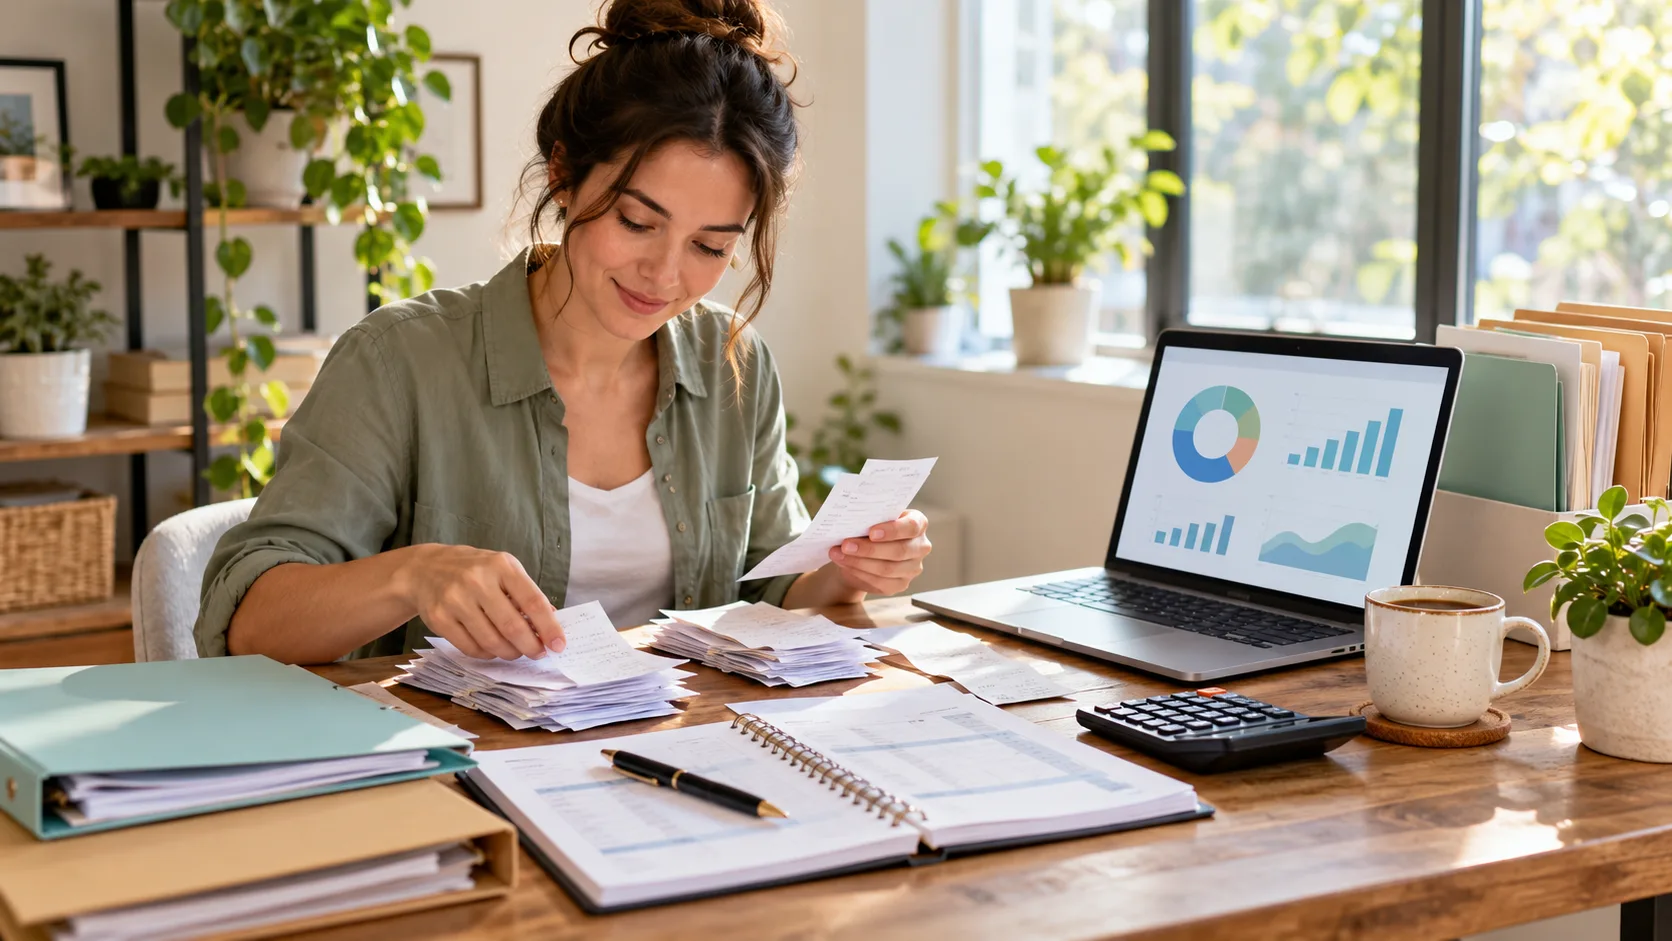
Bookkeeping is the process of recording and organizing a business’s financial transactions. These records may include sales, customer payments, supplier bills, payroll, loans, and purchases. Keeping the information current helps a business understand what money came in, what went out, and what it still owes or is owed.
Bookkeeping creates the organized financial records that owners use to make business decisions. A clear record can help answer practical questions: Are customers paying on time? Which expenses are increasing? Is there enough cash to cover upcoming bills? Without consistent records, it becomes harder to see how the business is performing.
Bookkeeping and accounting are related, but they are not the same task. Bookkeeping focuses on recording and organizing transactions, while accounting often involves interpreting financial information, preparing reports, and advising on decisions. In a small business, one person may handle both, but they require different skills and responsibilities.
Why Bookkeeping Matters to a Business
Accurate bookkeeping gives business owners a clearer picture of their finances. By reviewing income, expenses, unpaid invoices, and upcoming bills, they can make more informed choices about spending and growth. Regular records can also reveal patterns, such as seasonal sales changes or rising supplier costs, before they become harder to manage.
Organized records help a business prepare financial statements and support routine administrative tasks. Depending on local requirements, they may also help when filing taxes, applying for financing, responding to an audit, or sharing information with an accountant. The specific documents and retention rules vary by location, so owners should check the requirements that apply to them.
Bookkeeping can also help prevent small issues from becoming larger problems. For example, recording invoices and payments consistently makes it easier to notice late customer payments or duplicate expenses. When records are updated regularly, business owners can review reliable information instead of trying to reconstruct transactions from old receipts and bank statements.
What Transactions Does a Bookkeeper Record?
Bookkeepers typically record money received from customers, including sales, service fees, and other business income. They also record expenses such as rent, supplies, software subscriptions, utilities, travel, and payments to contractors. Each transaction should have enough detail to explain what it was, when it happened, and how it relates to the business.
Other records may cover accounts receivable, accounts payable, loans, payroll, inventory, and owner contributions or withdrawals. Accounts receivable tracks money customers still owe, while accounts payable tracks bills the business needs to pay. A bookkeeper may also organize supporting documents, such as invoices, receipts, contracts, and bank statements.
The exact transactions a business tracks depend on its size, industry, and structure. A retail shop may need detailed inventory records, while a consultant may focus more on client invoices and project expenses. Setting up categories that reflect how the business actually operates makes reports easier to understand and more useful.
How the Bookkeeping Process Works
Bookkeeping follows a repeating cycle. A business first collects evidence of a transaction, such as a receipt, invoice, sales record, or bank entry. The transaction is then classified and entered in the bookkeeping system, with the date, amount, account category, and relevant customer or supplier information.
The bookkeeper periodically compares internal records with bank and payment platform statements. This process, called reconciliation, helps identify missing transactions, duplicate entries, bank fees, or recording errors. If a discrepancy appears, the bookkeeper investigates it and updates the records only when there is enough information to support the correction.
At the end of a reporting period, the business reviews its records and prepares summaries or financial reports. How often this happens depends on the business’s needs, but monthly reviews are common because they help owners notice changes in a timely way. A consistent bookkeeping routine makes year-end work less rushed and easier to verify.
Single-Entry and Double-Entry Bookkeeping
Single-entry bookkeeping records each transaction once, often as money received or money spent. It can be straightforward for a very small business with simple finances and few transactions. However, it may not show the full effect of transactions on the business, making it harder to identify certain errors or prepare detailed financial statements.
Double-entry bookkeeping records each transaction in at least two accounts, using debits and credits. For example, when a business receives payment for an invoice, the entry may increase cash and reduce accounts receivable. The method is more structured and supports a fuller view of assets, liabilities, income, and expenses.
Many accounting systems use double-entry bookkeeping behind the scenes, even when the interface looks simple. This method helps keep the books balanced and can make reports more complete. Businesses with inventory, loans, employees, or plans to grow often benefit from a system that supports double-entry records and proper financial reporting.
Common Bookkeeping Terms for Beginners
A chart of accounts is the list of categories a business uses to organize transactions. Typical categories include income, operating expenses, assets, liabilities, and equity. A well-designed chart of accounts is detailed enough to answer useful questions but not so complicated that the owner and bookkeeper struggle to choose the right category.
Assets are resources the business owns or controls, such as cash, equipment, inventory, or amounts customers owe. Liabilities are obligations, including loans, unpaid supplier bills, and other amounts the business must pay. Equity generally represents the owner’s interest in the business after liabilities are accounted for, though its exact presentation depends on the business structure.
Revenue is income earned through business activity, while expenses are costs incurred to operate. Profit is generally what remains after expenses are subtracted from revenue over a period. Cash flow tracks the movement of money into and out of the business, which is related to profit but not identical to it.
Cash Basis and Accrual Basis Bookkeeping
Under cash basis bookkeeping, income is generally recorded when payment is received, and expenses are recorded when they are paid. This approach can be easier to understand because it follows the movement of cash. However, it may not show unpaid customer invoices or bills that have been received but not yet paid.
Accrual basis bookkeeping records income when it is earned and expenses when they are incurred, even if cash moves later. For example, a completed service may be recorded as revenue before the customer pays the invoice. This approach can give a fuller view of business activity during a period, especially when there are many outstanding invoices or bills.
The appropriate method may depend on the business’s needs, size, reporting goals, and local rules. Switching methods can affect how financial activity appears over time, so it should be planned carefully. A business owner can discuss the right approach with a qualified accountant or bookkeeper familiar with the rules that apply in their jurisdiction.
Bookkeeping Software, Spreadsheets, and Paper Records
Bookkeeping software can organize transactions, store receipts, create invoices, and generate financial reports. Some tools connect to business bank accounts or payment platforms, which can reduce manual data entry. Automation still needs review, since software may assign the wrong category or import duplicate transactions.
A spreadsheet can work for a small business with few transactions, especially when the owner understands how to maintain it. It should include consistent categories, dates, descriptions, amounts, and supporting-document references. As the number of transactions grows, spreadsheets may become harder to reconcile and more vulnerable to accidental changes.
Paper records can still be useful for receipts, signed agreements, or documents received offline, but they need a reliable filing system. Many businesses scan or photograph documents and store them securely with clear names and dates. Whichever method you choose, protect financial information, control access, and keep backups.
A Simple Bookkeeping Routine for Small Businesses
Start by separating business and personal finances wherever possible. A dedicated business bank account and payment method make transactions easier to identify and reduce confusion during reconciliation. If a personal expense is paid using business funds, record it correctly rather than leaving it mixed into ordinary operating costs.
Set a regular schedule for entering transactions and reviewing documents. For example, update the books weekly, send invoices promptly, follow up on overdue payments, and reconcile accounts monthly. A predictable routine helps prevent a backlog of receipts and gives the owner a more current view of cash and outstanding obligations.
Keep a simple checklist for recurring tasks, such as categorizing expenses, reviewing unpaid invoices, recording payroll, and saving supporting documents. Treat the work as an ongoing business process rather than a once-a-year cleanup. A little knowledge of project management basics can help owners assign tasks, set deadlines, and track completion.
Common Bookkeeping Mistakes to Avoid
One common mistake is waiting too long to record transactions. Memories fade, receipts go missing, and it becomes harder to match payments with invoices. Entering records regularly makes it easier to spot unusual activity while the details are still available.
Another frequent problem is misclassifying transactions or mixing personal and business spending. A purchase may appear obvious at first, but unclear descriptions can make it difficult to understand later. Keep receipts, add brief notes when needed, use consistent account categories, and ask for help when a transaction is uncertain.
Skipping bank reconciliation can allow errors to remain unnoticed. A bank statement may include charges, refunds, or payments that were not entered in the bookkeeping system. Compare records routinely, investigate differences, and do not force the books to balance by adding unexplained adjustments.
When to Hire a Bookkeeper or Accountant
A business owner may be able to manage basic bookkeeping when transaction volume is low and finances are straightforward. As the business grows, tasks such as payroll, inventory tracking, multiple accounts, and overdue invoices can take more time. Hiring a bookkeeper may free the owner to focus on customers and operations.
A bookkeeper typically records transactions, organizes documents, reconciles accounts, and prepares routine reports. An accountant may handle more complex analysis, financial statements, tax planning, or advice, depending on their qualifications and local rules. Some professionals offer both services, so clarify responsibilities before handing over records.
When selecting a professional, ask about their experience with businesses of similar size and industry. Discuss software, reporting frequency, document security, fees, and who will review the work. Good communication matters: the owner should understand the reports well enough to make decisions and ask questions.
Conclusion
Bookkeeping is the routine process of recording, categorizing, and organizing a business’s financial transactions. It helps owners track income, expenses, cash flow, unpaid invoices, and bills, while creating records that support reporting and other business tasks.
A reliable bookkeeping system can use software, spreadsheets, or a combination of tools. What matters most is consistency: record transactions promptly, keep supporting documents, reconcile accounts, and review the numbers regularly.
As a business grows, its bookkeeping needs may change. Start with a clear routine, use categories that fit the business, and seek professional help when transactions or reporting requirements become more complex.
FAQs
What is bookkeeping in simple terms?
Bookkeeping is the process of recording and organizing a business’s financial transactions. It helps track money received, expenses paid, unpaid invoices, bills, and other financial activity.
What is the difference between bookkeeping and accounting?
Bookkeeping records and organizes transactions. Accounting uses those records to prepare reports, interpret financial results, and support planning or other financial decisions.
Can I do bookkeeping myself?
Yes, owners of small businesses with simple finances may manage their own books using software or spreadsheets. Regular updates, document storage, and bank reconciliation are essential.
What records should a small business keep?
Common records include invoices, receipts, bank statements, payroll information, bills, loan documents, and sales records. Requirements and retention periods vary, so check the rules in your location.
When should a business hire a bookkeeper?
Consider hiring one when transaction volume grows, records fall behind, or tasks such as payroll and reconciliation take time away from running the business.